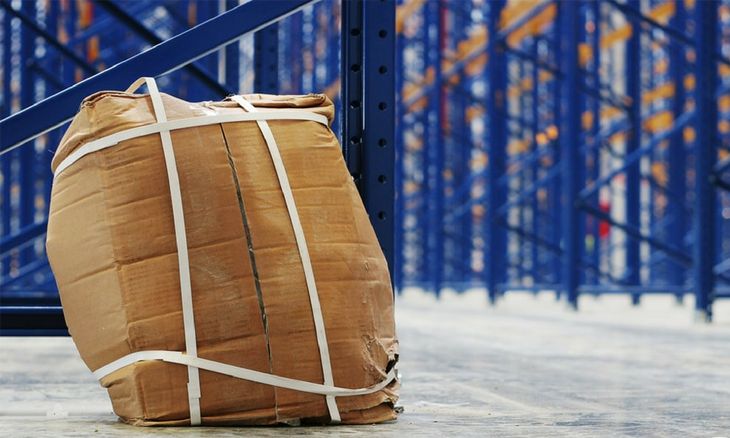
Cargo insurance pays financial compensation when goods are lost or damaged during shipping. It may apply to many types of transportation. A business can buy it through the shipping provider or a third-party insurer. Even well-packed shipments face risks in transit, so cargo insurance gives shippers a way to cover losses.
Why Should You Consider Cargo Insurance?
No single company controls everything that happens to a shipment between origin and destination. Weather, handling and road conditions can all affect a crate along the way.
Even items packed with care can suffer damage during transportation. The risk may be low, but it is rarely zero. That makes cargo insurance worth a look for any business shipping valuable assets.
Working with a specialty crating and shipping provider is one part of protecting a shipment. Alliance Relocation Services offers a custom crating and uncrating service across the United States and Canada. Pairing that kind of packing with a cargo insurance policy adds a second layer of protection for the parts of the trip no provider can fully control. See How Specialty Crating Differs from Conventional Relocation Services.
What Is Cargo Insurance?
Cargo insurance pays compensation when goods are damaged or lost while in transit. Merriam-Webster defines it as insurance against loss from damage to goods carried by motor truck, though the same idea may apply to many types of transportation.
Insuranceopedia describes cargo insurance as protection for the owner or consignor of goods against physical loss or damage from outside causes during shipping. The insurer reimburses the policyholder for the value of goods that are damaged or lost while in the hands of the shipper. A business can buy this coverage from the shipping company itself or from a separate insurer.
In plain terms, cargo insurance pays financial compensation if a shipment is destroyed or damaged on its way to its destination. A business can choose its insurance provider, or the crating and shipping company handling the job may suggest a preferred one.
What Types of Cargo Insurance Coverage Are There?
Cargo insurance generally falls into four main categories:
- Standard cargo insurance. Sometimes called all-risk coverage, this protects assets against nearly any type of insurance risk. It can cover equipment, machinery, furniture, artwork and electronics.
- Limited liability insurance. Also called lost-only coverage, this applies when clients pack their items themselves. It skips visible or concealed damage but covers a full container or shipment that is stolen or goes missing.
- Job Service Order (JSO) insurance. This covers the packing process only. This coverage typically applies only to local transportation for items packed in a crate or corrugated box. Items shipped by a common carrier fall outside this policy.
- Used electronics and machinery insurance. This applies to items over one year old, and it typically covers visible damage only.
Packing choices affect how well a shipment holds up regardless of the policy in place. See Shipping Breakables Takes Important Knowledge and Preparation.
What Are Cargo Insurance Endorsements?
An endorsement, also called a rider, adjusts the terms of a base cargo insurance policy. It can add, remove or change coverage details to match a specific shipment.
For example, one item in a large shipment may carry far more value than the rest. A business can purchase a rider to add protection for that single item. Endorsements let a company shape a policy around its actual needs instead of settling for a generic one.
How Do You Choose Cargo Insurance That Fits Your Business?
Start by estimating the total value of the assets being shipped. A rough guess usually leads to the wrong amount of coverage, either too little or too much money spent on protection that isn’t needed.
Next, weigh the risks the shipment will face in transit and what you want the policy to protect against. Do this for one shipment at a time, since conditions and contents change from one job to the next.
Cargo insurance tends to offer solid protection for a reasonable cost. It can be tempting to assume the shipping company will take care of everything. Even skilled, experienced crews cannot control outside events like another vehicle colliding with the truck carrying a shipment.
Having the right cargo insurance in place means a damaged or destroyed asset doesn’t turn into an unplanned expense your company has to absorb or explain. Request a quote to talk through crating options for an upcoming shipment.
Frequently Asked Questions
What Does Standard Cargo Insurance Cover?
Standard cargo insurance, often called all-risk coverage, protects assets against nearly any type of insurance risk. It can cover equipment, machinery, furniture, artwork and electronics.
Can You Insure a Single High-Value Item Within a Larger Shipment?
Yes. An endorsement, or rider, can add coverage for one item worth more than the rest of a shipment. This lets a business adjust a cargo insurance policy without replacing the base coverage.
Where Can a Business Get Cargo Insurance?
A business can buy cargo insurance from the shipping company itself or from a separate insurer. The crating and shipping company handling the job may also suggest a preferred provider.
Is Limited Liability Insurance the Same as Full Coverage?
No. Limited liability, or lost-only, insurance applies mainly when clients pack items themselves and covers a missing container or shipment. It does not cover visible or concealed damage, which standard cargo insurance does.